Illustrative Sample — Not Available for Funding.
Deal Locker Preview

See the deal. Understand the risks. Ask better questions.

This page demonstrates the proposed Deal Locker format — how a deal presentation and a borrower update could be organized inside Be the Bank Club. Every name, figure, document and review status below is fictional. No real property, borrower or loan is shown, and no actual checks have been performed.

Available with membership todayEducation, community, and applicable borrower-readiness and vetting resources, as described on the membership page.
Proposed — shown here as a demonstrationThis standardized deal layout, readiness table, document checklist and monthly update format. Features and layout may change and are not all operational yet.
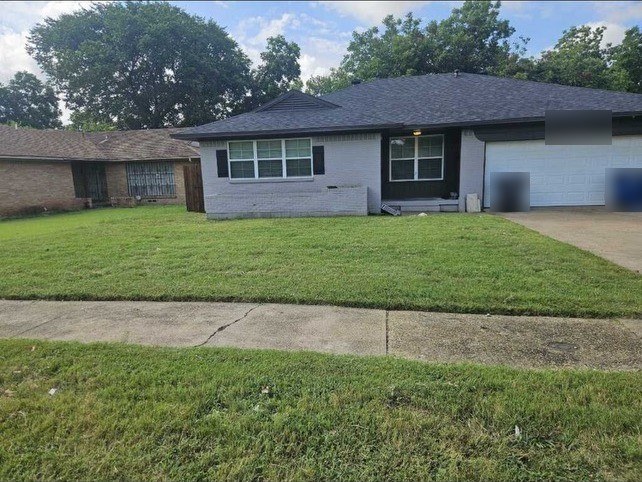
Front view of a single-story house with a two-car garage and a lawn. Representative photo of a different property, not the Oak Street sample.Representative photo
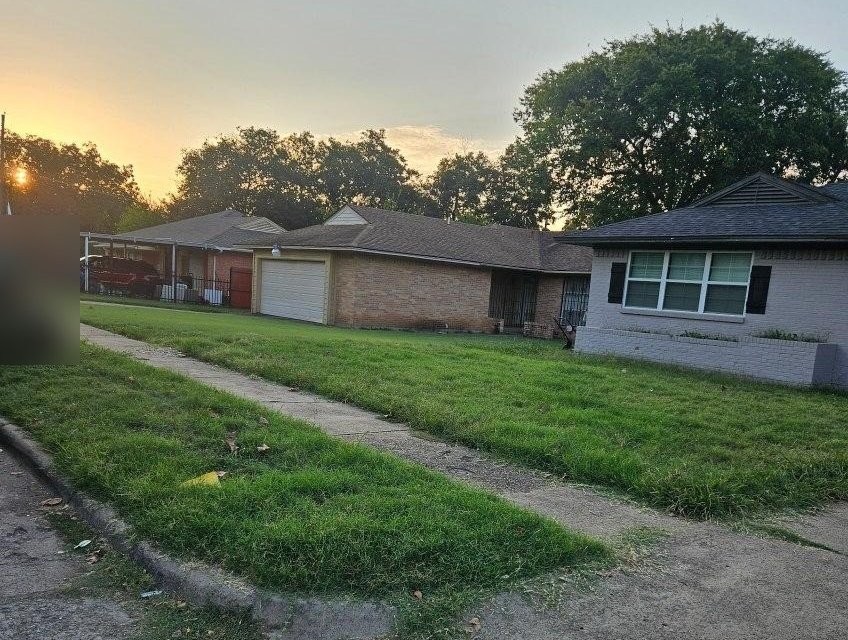
Street view at sunset of the same house and neighboring homes. Representative photo of a different property, not the Oak Street sample.Representative photo
Illustrative images—not the actual property. These photos show a different house, used only to illustrate the format. They are not the Oak Street sample, not a listing, and not progress photos. The house number and a bystander have been obscured.
Fictional sample

Oak Street Renovation

Tampa, Florida · Three-bedroom single-family fix-and-flip
Borrower
Oak Street Property Group LLC (fictional)
Scope
Kitchen and bathroom updates, flooring, interior paint, and landscaping
Loan request
$180,000
Proposed interest
11% annually, interest-only
Monthly interest
$1,650 on the full loan balance
Proposed term
12 months
Proposed security
First-position mortgage, subject to title confirmation and recording
Primary exit
Sale after renovation
Timeline
Six-month target project timeline; loan maturity at 12 months
Review status (sample): Additional review required. This fictional deal is not approved and is not available for funding.
Project Numbers · Sample

The key figures, up front

All figures are fictional and shown for format only.

Requested loan
$180,000
11% interest-only · 12-month term
Total projected cost
$235,000
Purchase, renovation, costs & contingency
Borrower cash
$55,000
$235,000 cost − $180,000 loan
Loan-to-projected-ARV
60%
$180,000 ÷ $300,000 illustrative ARV
Project budget
ItemAmount
Purchase$150,000
Renovation$45,000
Closing, holding and selling costs$30,000
Contingency$10,000
Total projected cost$235,000
Requested loan$180,000
Borrower cash contribution$55,000
Interest and delays. The $30,000 cost allowance includes interest for the six-month target timeline (6 × $1,650 = $9,900). Each additional month adds about $1,650 in interest, plus other holding costs — so delays can push costs beyond this budget.
Valuation & projected margin
MeasureSample figure
Illustrative after-repair value (ARV)$300,000
Loan-to-projected-ARV60%
Projected sale proceeds less total project cost$65,000
The ARV is an illustrative assumption. A real submission would need comparable sales and supporting analysis. Loan-to-ARV does not establish current collateral value or guarantee recovery. The $65,000 projected margin is before income taxes and any costs beyond the budget — it belongs to the project and is not a lender return.
Borrower Readiness · Example statuses only

Borrower readiness

These statuses are fictional. No actual identity, entity, background, credit, experience or reference checks have been performed. Each status is written out in text.

ItemStatus (sample)
Required educationComplete
Identity / entity documentationReviewed
ExperienceThree completed projects documented
Prior lender referencesTwo reviewed
Background / credit reviewPending — not yet complete
Reporting standards acknowledgmentComplete
Overall status (sample): Additional review required. The borrower and the deal are not approved.
Due Diligence

Risks, questions and documents

Tap a heading to expand it.

Lender review questionsSix questions a lender would want answered
  • Does the valuation hold up against comparable sales?
  • Are the contractor bids, scope and contingency adequate?
  • Does title support the proposed lien position?
  • What insurance is required?
  • Can the borrower cover overruns and delays?
  • What realistic alternatives exist if the sale is delayed?
Key risks in this sampleWhat could change the outcome
  • Valuation risk: the $300,000 ARV is an assumption, not an appraisal or comparable-sales analysis.
  • Schedule and cost risk: each month beyond the six-month target adds about $1,650 in interest plus holding costs that are not in the budget.
  • Lien and title risk: first position depends on title confirmation and recording.
  • Exit risk: the plan relies on a sale; market conditions could delay or reduce proceeds.
  • Borrower risk: background and credit review is pending in this sample.
Outstanding documents5 items not yet provided in this sample
  • Title report — Outstanding
  • Independent valuation review — Outstanding
  • Final contractor agreement — Outstanding
  • Insurance evidence — Outstanding
  • Completed borrower screening — Outstanding
Borrower Update · Sample

Sample monthly update

How a borrower could report progress to lenders each month. Fictional content.

Month 2 update — Oak Street Renovation

Schedule: Behind by two weeks

Completed

Demolition, rough plumbing, and electrical.

Renovation spending

$18,000 of $45,000 (40% of renovation budget)

Next work

Drywall, cabinets, and flooring.

Issue

Cabinet delivery delayed two weeks.

Response

Contractor resequenced work; target listing moved from Month 4 to Month 5.

Next update

Due in 30 days, with material changes reported sooner.

Evidence: A real update would include progress photos and invoices. None are attached to this sample.

Lend and borrow with clearer information.

Membership offers Lender, Borrower and Dual-Track options. Current members can sign in to the member portal.

Disclosure. This preview is fictional and for demonstration only. It is not an offer to lend or invest, a borrower approval, or a commitment to provide funding. Members make their own decisions, conduct independent due diligence, and involve qualified professionals as appropriate. Private lending involves risk, including loss of principal.

Private Lending Society

Legal

Be the Bank Club is a private lending community, not a registered investment advisor. Private lending involves risk. Past performance does not guarantee future results. All lending decisions are made directly between individual members. Be the Bank Club does not originate, service, or guarantee any loan.

© 2025 Be the Bank Club. All rights reserved.